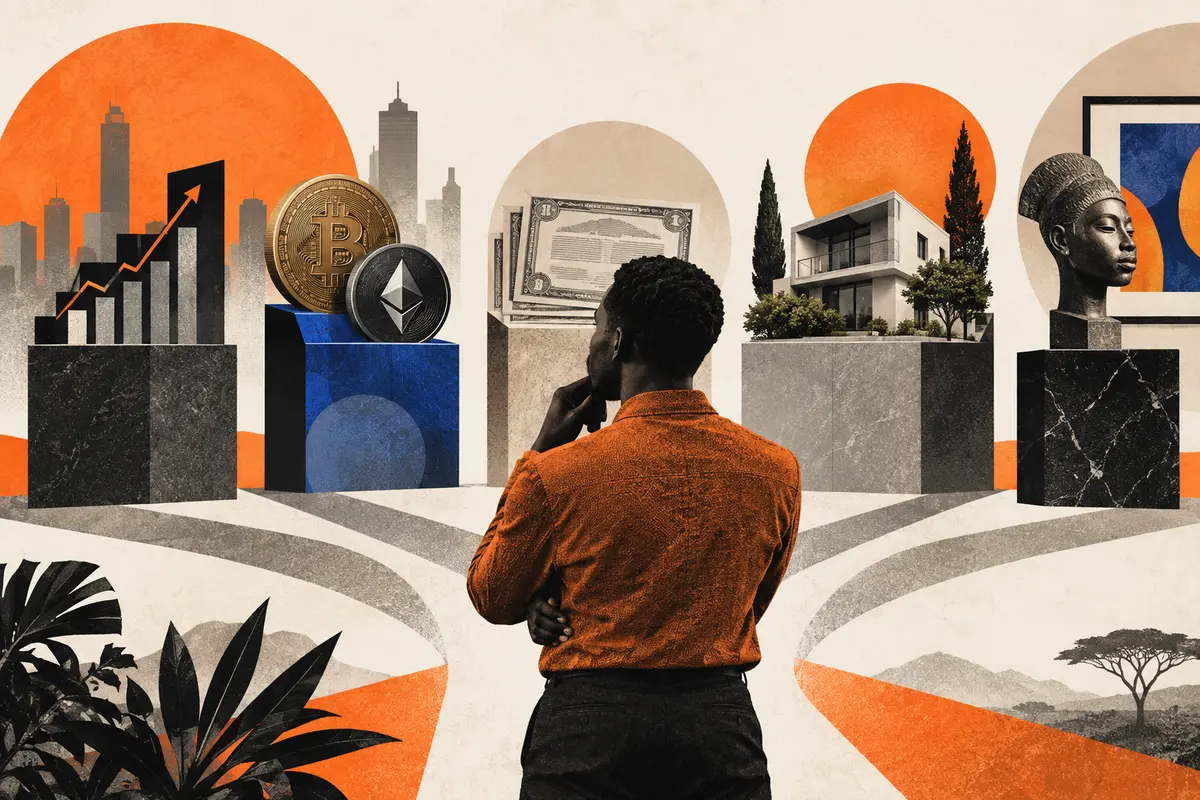
A good opportunity becomes a problem when you have to sell it at the wrong time to pay an urgent bill. Before choosing where to invest, decide which money needs to stay available.
Think of a rent deadline, an unexpected medical bill or a temporary loss of income. Money for those needs has a different job from money set aside for a goal several years away. Its first job is to be there when you need it.
Access is part of the return
A product may advertise an attractive rate but lock your money until maturity, charge for early withdrawal or take several days to pay out. Those terms matter as much as the quoted yield when the money is your safety buffer.
There is no single amount that fits everyone. Start with your essential monthly costs, the stability of your income and the people who depend on you. A freelancer with uneven earnings may want a different buffer from someone with a stable salary and few fixed commitments.
Give each amount a job
Keep near-term spending and emergency money in places you understand and can access reliably. For goals further away, you can consider more volatility or a longer commitment if the possible return is worth the risk to you. The split can change as your circumstances change.
If you needed this money quickly, what would it take to get it back and how much could you lose?
Try this before moving your money
- List the expenses that cannot wait and the dates they are due.
- Check withdrawal timing, penalties and any limits for each account or investment.
- Keep an accessible reserve that reflects your own income and obligations.
- Invest the remainder according to the goal and the time you can leave it untouched.
Holding accessible cash has an opportunity cost, and inflation can erode it. But being forced to sell a long-term investment at a bad moment has a cost too. Your plan should account for both.
Sources and method
Means by ActiveMeans. Educational information, not personalised investment advice. Investments can lose value.
← Back to Means